TD personal loan online application sounds straightforward until you hit the first screen. Only existing TD customers can apply online through EasyWeb. New customers get redirected to book a branch appointment.
That single restriction changes the math for anyone comparison-shopping lenders right now. If you don't already bank with TD, your "quick online application" turns into a weekday trip.
This guide is for Canadians who already hold a TD chequing or savings account and want to know exactly what the online process looks like in 2026, what TD charges, and where the friction sits.
How Much Can You Borrow with a TD Personal Loan?
TD personal loans in Canada range from $5,000 to $50,000, with repayment terms of 1 to 7 years. Borrowers pick between fixed and variable interest rates at the time of application.
TD Personal Loan Amounts and Terms
The $5,000 minimum is higher than what some borrowers need. If you only want $2,000 or $3,000, TD's personal loan product won't work. A TD Personal Line of Credit might, but that's a different product with different repayment rules.
Repayment frequency is flexible. You can set up weekly, bi-weekly, semi-monthly, or monthly payments through your TD account. Most borrowers default to monthly, but bi-weekly payments reduce total interest paid over the life of the loan.
TD Personal Loan Interest Rates in 2026
TD does not publish its personal loan interest rates on the TD Canada Trust website. You won't see a rate until you log in and request a personalized quote.
Ratehub's 2026 comparison lists TD personal loan rates between 8.99% and 23.99% APR. That's a wide spread. Your credit score, income, and existing relationship with TD all determine where you land.
I think the 8.99% floor is competitive against CIBC's 9% starting rate, but the 23.99% ceiling tells you something.
TD clearly prices risk aggressively on the higher end. A borrower with a 650 credit score and a borrower with a 780 will see very different offers.
The Online Application Process Step by Step
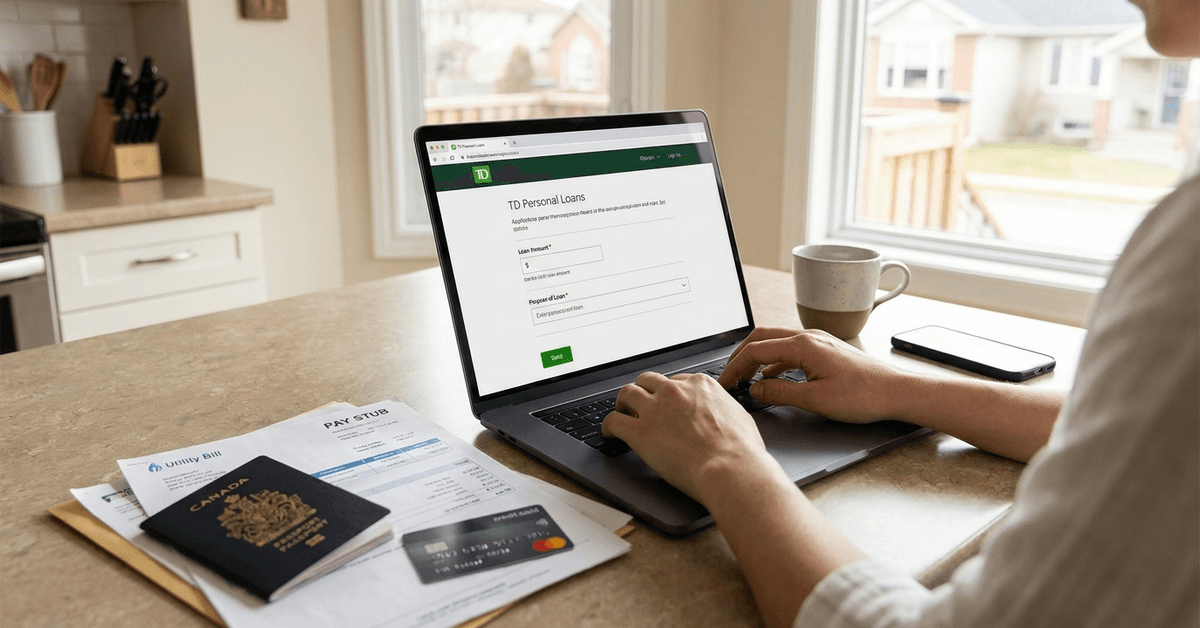
TD's online personal loan application requires an existing EasyWeb login. If you have a TD username, access card, or Connect ID, you can start immediately.
What You Need Ready
TD's application checklist asks for specific documents. Have these pulled up before you start:
- Government-issued photo ID (driver's license or passport, original and not expired)
- Proof of income: last two paystubs if employed, or last two Notice of Assessment documents if self-employed
- Expense statements: mortgage or rent payments, utility bills, tax documents, and any existing credit statements
- Bank account details for deposit of funds and repayment scheduling
Filling Out the Application
The digital form walks through personal information, employment status, monthly income, and existing debts. TD uses this data alongside a hard credit inquiry to generate your rate.
One thing that trips people up: TD asks for your intended loan purpose. Options include debt consolidation, home renovation, and major purchases. The category you pick may affect which verification steps TD runs.
After submission, you get a confirmation screen. TD may contact you within one business day for follow-up documents or clarification. Some applications get preliminary decisions faster, but complex cases take a few business days.
Fixed vs. Variable Rate: Which One to Pick
TD lets you choose between a fixed rate and a variable rate on personal loans. Fixed keeps your payment identical every month. Variable ties your rate to the TD Prime Rate, so payments shift when prime moves.
When Variable Might Save You Money
I would pick variable on a TD personal loan only if the term is 3 years or shorter. On a $15,000 loan over 36 months, a 1% difference between variable and fixed saves roughly $240 in total interest.
On a 7-year term, that same rate swing could cost you over $1,000 if prime climbs. Most personal finance advice says fixed is always safer.
I'd push back on that for short-term TD loans specifically, because the Bank of Canada's rate trajectory through late 2026 has been relatively stable, and locking in a higher fixed rate for 36 months when variable sits lower just hands TD free margin.
No Prepayment Penalty
TD does not charge a penalty for paying off your personal loan early. If you get a bonus, a tax refund, or just want to throw extra cash at the balance, you can make lump-sum payments without a fee.
This is a genuinely useful feature. Some online lenders charge 2% to 5% of the remaining balance as a prepayment penalty. TD charges zero.
Who Gets Approved and Who Doesn't
TD does not publish a minimum credit score requirement for personal loans. The bank reviews each application based on what it calls your "overall financial profile," which includes income, assets, existing debts, and credit history.
Eligibility Basics
You need to be a Canadian resident who has reached the age of majority in your province or territory.
A regular, verifiable income source is required. Self-employed applicants qualify but need to provide Notice of Assessment documents instead of paystubs.
Co-signers are allowed. If your credit or income alone doesn't meet TD's threshold, adding a co-applicant can strengthen the application. Both people need to submit full documentation.
What Happens If TD Says No
A declined application still leaves a hard inquiry on your credit report. That inquiry stays for about two years through Equifax or TransUnion Canada.
If TD declines you, ask for specific feedback. Sometimes the issue is a debt-to-income ratio, not the credit score itself. Paying down an existing balance by even a few hundred dollars can change the outcome on a second attempt 60 to 90 days later.
TD Personal Loan vs. TD Line of Credit
The personal loan is better when you know exactly how much you need and want a fixed payoff date. The line of credit works better for ongoing or unpredictable expenses where you might borrow, repay, and borrow again.
| Feature | TD Personal Loan | TD Personal Line of Credit |
|---|---|---|
| Loan amount | $5,000 to $50,000 | Up to $50,000 |
| Rate type | Fixed or variable | Fixed or variable |
| Term | 1 to 7 years | Open-ended (revolving) |
| Repayment | Scheduled installments | Minimum monthly payment |
| Prepayment penalty | None | None |
I think most Canadians looking at debt consolidation should pick the personal loan over the line of credit. A line of credit with open-ended access makes it too easy to re-borrow what you just paid down.
The fixed installment structure of a personal loan forces discipline that a revolving credit line does not.
Common Mistakes During the TD Loan Application
The online process is fairly clean, but a few errors show up repeatedly.
Income Reporting Gaps
Small discrepancies between your paystub numbers and what you enter in the application can trigger a manual review.
TD flags these inconsistencies, and manual reviews add days to the timeline. Use your most recent paystub and copy the numbers exactly.
Forgetting About Existing TD Products
TD can see every product you hold with them. If you have an existing TD credit card with a high balance or a line of credit near its limit, that data factors into your debt-to-income ratio automatically.
Pay down TD-held balances before applying. The bank's internal data gives them a more complete picture of your finances than a credit bureau report alone.
Questions People Ask About TD Personal Loans in Canada
These are the searches that keep popping up, answered without the fluff.
- Q: Can I apply for a TD personal loan online if I'm not a TD customer?
No. TD requires an existing EasyWeb login, access card, or Connect ID for online applications. New customers need to book a branch appointment or call TD directly to start the process in person. - Q: How fast does TD deposit personal loan funds after approval?
TD typically deposits funds within one to three business days after you sign the loan agreement. Some borrowers report same-day funding when the application goes through without manual review, but that's not guaranteed. - Q: Does applying for a TD personal loan hurt my credit score?
TD runs a hard credit inquiry when you submit a full application. That inquiry can drop your score by 5 to 10 points temporarily and stays on your report for about two years. Checking your personalized rate quote through EasyWeb does not trigger a hard pull. - Q: Can I use a TD personal loan for anything I want?
TD allows personal loan funds for most purposes, including debt consolidation, home renovations, medical expenses, and major purchases. The bank does not restrict how you spend the money after disbursement, but the purpose you select during application may affect verification steps. - Q: What's the difference between TD's fixed and variable personal loan rates?
Fixed rates stay the same for the entire loan term, giving you identical monthly payments. Variable rates move with the TD Prime Rate, so your payment amount can change. Fixed offers predictability. Variable can cost less if prime stays flat or drops, but carries risk if rates rise.
Conclusion
TD's personal loan product is solid for existing customers who want predictable payments and no hidden fees. The 8.99% to 23.99% APR range means your credit profile determines everything, so check your rate quote through EasyWeb before committing.
If you're new to TD, prepare for a branch visit instead of a quick online form. And if your loan term is under three years, run the variable rate numbers before automatically locking in fixed.