A Scotiabank personal loan can be paid off early with no prepayment penalty. That one quiet rule should shape how you pick your term, long before you ever click "apply."
Terms usually run from one to five years. The shorter one looks responsible on paper, and it also locks you into the biggest required payment every single month.
This guide is for Canadians in 2026 juggling a few high-interest balances who want one fixed payment and a firm finish line, without a budget that snaps the first time the car needs tires.
What Is a Scotiabank Personal Loan, and Can It Consolidate Debt?
A Scotiabank personal loan is an installment loan: you borrow a lump sum once, then repay it in fixed payments until a set end date. For debt consolidation, that structure does the heavy lifting.
Several card balances become one payment with a known final date, and nothing gets borrowed back. You always know when the debt ends and roughly what each month costs.
It also covers one-time costs like a home renovation or tuition. If your expenses arrive in irregular waves instead, a line of credit may fit better, and I compare both further down.
How to Apply for a Scotiabank Personal Loan Online
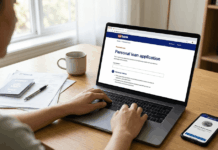
You apply through Scotiabank's personal loan page by choosing an amount and term, completing a secure form, uploading documents, and waiting for a decision that often arrives within minutes.
The Online Application, Step by Step
Start on the official Scotiabank personal loans page, pick your loan amount, term, and repayment option, then fill in accurate personal and employment details.
Next, upload what they request, usually ID and proof of income. Larger loans can trigger extra verification, so a slower decision on a bigger amount is normal.
What Happens After You Click Submit?
Approved funds land directly in your bank account, usually within one business day. Repayments then start on the schedule written into your loan agreement.
Branch and phone applications still exist if you'd rather talk to a person. Applying online simply skips the appointment and the waiting room chairs.
Who Qualifies for a Scotiabank Personal Loan in 2026?
You qualify if you're a Canadian resident of legal age in your province with a stable income from employment or recurring benefits, plus acceptable credit.
Scotiabank publishes no fixed minimum credit score. A stronger score still improves your approval odds and the rate you get offered, since the bank reviews your full financial picture.
Documents to Have Ready
Gathering these before you open the form speeds up the whole process:
- Government-issued photo identification
- Recent pay stubs or proof of recurring benefits income
- Recent bank statements
- A current bill showing your address, if residency proof is requested
Check Your Credit Report First
Pull your reports from Canada's two credit bureaus, Equifax and TransUnion, and dispute any errors first. The Financial Consumer Agency of Canada explains how to get your report for free.
An old account wrongly marked as unpaid can cost you a better rate. Fixing it takes some effort, and that effort pays off before an application, not after.
Should You Pick a 1-Year or 5-Year Loan Term?
Pick the longest term you'd be comfortable carrying, then repay it like a shorter one. Scotiabank personal loan terms commonly run from one to five years, with no penalty for early repayment.
The standard line says to choose the shortest term you can afford, since shorter terms mean less total interest. I disagree for consolidators, because Scotiabank's no-prepayment-penalty rule turns the 5-year term into a cheap safety net.
The "Long Term, Short Payoff" Approach
Set your required payment at the 5-year level, then add extra every pay period as if you'd chosen a shorter term. A rough month means you drop back to the minimum.
A missed fixed payment lands on your credit report. A smaller extra payment only stretches your payoff a little, and no one at the bank sends you a scolding letter about it.
What's the Catch?
This only works with discipline. If the extra payments quietly stop, you pay more total interest than the shorter term would have cost you.
Rates also depend on your creditworthiness, loan amount, and term length. Scotiabank adjusts them periodically, so check the current rates page instead of trusting an old screenshot.
Do Biweekly Payments Help?
Payments can match your pay cycle, and some borrowers choose biweekly instead of monthly. Twenty-six half payments a year equal thirteen full monthly payments, which pays the loan down faster.
Scotiabank Personal Loan vs Line of Credit: Which One Fits?
A personal loan suits one known cost, while a line of credit suits ongoing, unpredictable expenses. A line of credit gives reusable access to funds up to an approved limit and may only require interest payments.
| Feature | Personal loan | Line of credit |
|---|---|---|
| How you get funds | One lump sum | Reusable up to your limit |
| Repayment | Fixed payments, set end date | May allow interest-only minimums |
| Best match | Consolidation or one-time purchase | Irregular, recurring expenses |
| Main risk | Higher required payment | Balance can linger for years |
If your goal is to finish paying something off, the fixed end date in the personal loan column is the feature you're shopping for.
Where Lines of Credit Trip Up Consolidators
An interest-only minimum feels light each month. Meanwhile the original balance can sit untouched, which is the exact situation a consolidation borrower is trying to escape.
My take: the reusable limit on a line of credit tempts people toward the same spending that built the debt. A personal loan closes that door once the funds are used.
Mistakes to Avoid Before Signing a Scotiabank Loan
The most common mistake is consolidating card debt and then running those cards right back up, a sequel nobody asked for. Watch for these too:
- Running balances back up on the cards you just paid off
- Accepting optional loan insurance without reading what it covers and what it adds to each payment
- Borrowing more than a written monthly budget supports
- Assuming the advertised rate is the rate you'll personally receive
Optional loan insurance is extra coverage that raises the cost of every payment on a Scotiabank personal loan. It may help some borrowers protect against job loss or illness, so review its terms carefully on Scotiabank's site.
So what would happen to your plan if your income dipped for two months? Answer that honestly before you sign, and the right term usually picks itself.
Questions People Ask About Scotiabank Personal Loans
These come up constantly, so here are quick answers.
- Q: Does Scotiabank charge a fee to pay off a personal loan early?
No, Scotiabank typically allows early repayment without penalties. That freedom is exactly why a longer term with extra payments can work for disciplined borrowers. - Q: Can I get a Scotiabank personal loan with bad credit?
Scotiabank does not publish a fixed minimum score, so applying is possible. Expect a weaker score to bring a higher rate or a smaller approved amount. - Q: How fast can I get money from a Scotiabank personal loan?
Online decisions often come within minutes, and funds usually arrive within one business day. Applications needing extra documents can take a bit longer. - Q: Can I apply for a Scotiabank personal loan without visiting a branch?
Yes, the full application works online, and phone applications are also available. A branch visit is optional for people who prefer face-to-face help. - Q: Is a Scotiabank personal loan good for debt consolidation?
It can be suitable if the rate beats your current card rates and you stop using those cards. Compare the total interest cost, not only the monthly payment.
Conclusion
A Scotiabank personal loan works best when you treat the term as a safety net rather than a deadline. The no-prepayment-penalty rule lets you choose flexibility now and still finish early when money allows.
Check your credit report, read the insurance terms, and compare current rates before submitting anything online. Then ask yourself one question: are you buying a finish line, or just a cheaper way to keep spending?